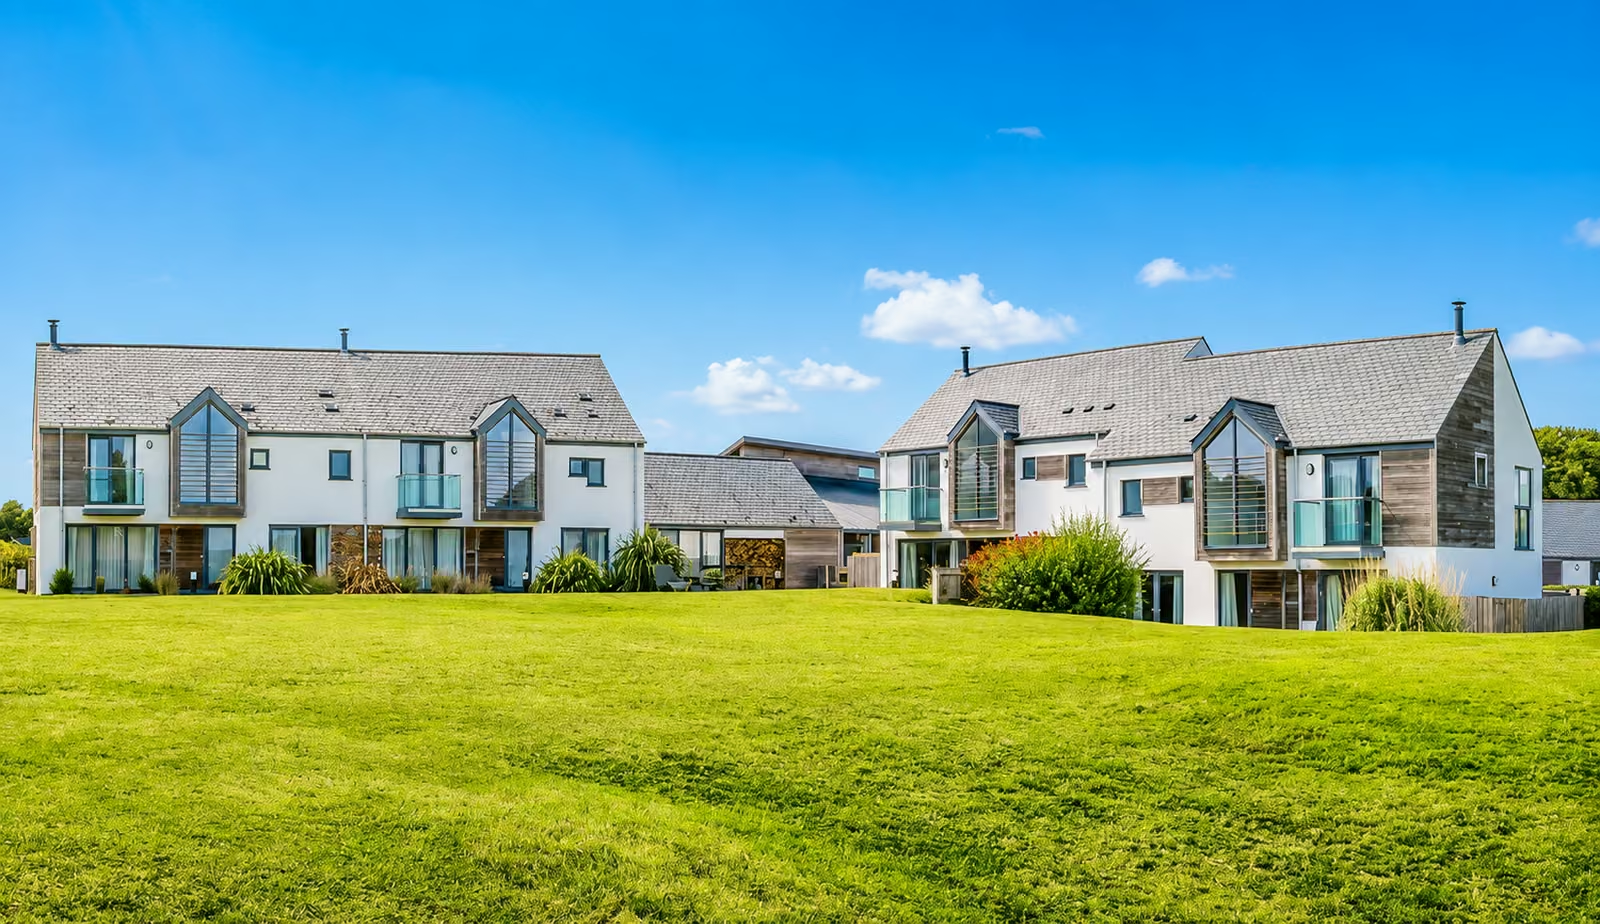
Last updated 10 November 2026
You can use a Whalesborough holiday home in every season of the year, but you cannot make it your main or only home. The lodges sit on a site with a 12-month holiday licence, and the terms for each other home are set out in its sales particulars. That one rule shapes three other things buyers ask about: council tax, stamp duty and how a purchase is funded. Each is covered below. Treat this page as a starting point for a conversation with your solicitor or tax adviser.
What does “holiday occupancy” mean?
Holiday occupancy is a planning or licence condition that lets a home be used for holidays at any time of year, while preventing anyone from living in it as their permanent or main residence. At Whalesborough it works like this:
- Lodges (Gwithva and Trelowen): the site holds a 12-month holiday licence, so your lodge is available all year round. The lodges are designed and licensed as holiday accommodation, not as a permanent residence.
- Gwelva Holiday Homes: held on a 999-year lease, with a 12-month holiday licence so the home can be enjoyed all year round.
- Cottages and Signature homes: the terms for each are set out in its sales particulars.
In practice, owners come for long weekends in February, spend whole weeks in summer and use the estate across the winter. What they cannot do is give up their main home and move in.
Why does a 12-month season matter?
Many holiday parks close for part of the year, while owners still pay fees for all twelve months. A 12-month season changes that: the more nights you use the home, the more value you get from it. At Whalesborough the season runs all year, and owners get complimentary W Club spa and gym membership and the run of the 428-acre estate in every month.
Do you pay council tax on a holiday lodge?
No. Gwithva and Trelowen lodges at Whalesborough do not pay council tax or business rates. Our cottages and Signature properties are subject to business rates. Whichever home you choose, it must stay a holiday home and not become your main residence.
Does the stamp duty surcharge apply to a holiday lodge?
Whether the second-home stamp duty surcharge applies depends on the property and the transaction, so the position can differ between the lodges, the cottages and the Signature homes. Your own position also depends on your circumstances, so speak to your solicitor or tax adviser before you buy. As general context only, GOV.UK says buyers in England will usually pay 5% on top of normal rates when a purchase means they will own more than one residential property. HMRC’s guidance lists property that is “moveable like a caravan, houseboat or mobile home (unless it has become a permanent fixture)” among the cases the higher rates do not apply to. How that applies to any particular home is a question for your solicitor.
Can you buy a holiday home with a mortgage?
Holiday-occupancy properties are often assessed differently from ordinary residential homes, so lending is not always straightforward. We work with established leisure-lending partners, and our sales team is happy to make an introduction.
Who is a Whalesborough holiday home right for?
It suits buyers who already have a main home and want a second place they can use in every season: long weekends, school holidays, a winter week by the sea. It does not suit anyone looking to sell up and live by the coast full time. To see how the year works before you decide, stay on the estate first and arrange your viewing around your visit. The lodges for sale and cottages for sale pages list every home with its price.
Sources: GOV.UK – SDLT residential rates · GOV.UK – Buying an additional residential property